
1. Seller-Paid Closing Costs (Concessions)
What it is: A seller-paid closing cost concession is money the seller agrees to contribute at closing, credited toward the buyer's closing costs, prepaids, or other allowable charges. It doesn't reduce the sale price — it reduces (or eliminates) what the buyer has to bring to the table, or it can be redirected to buy down the buyer's rate.
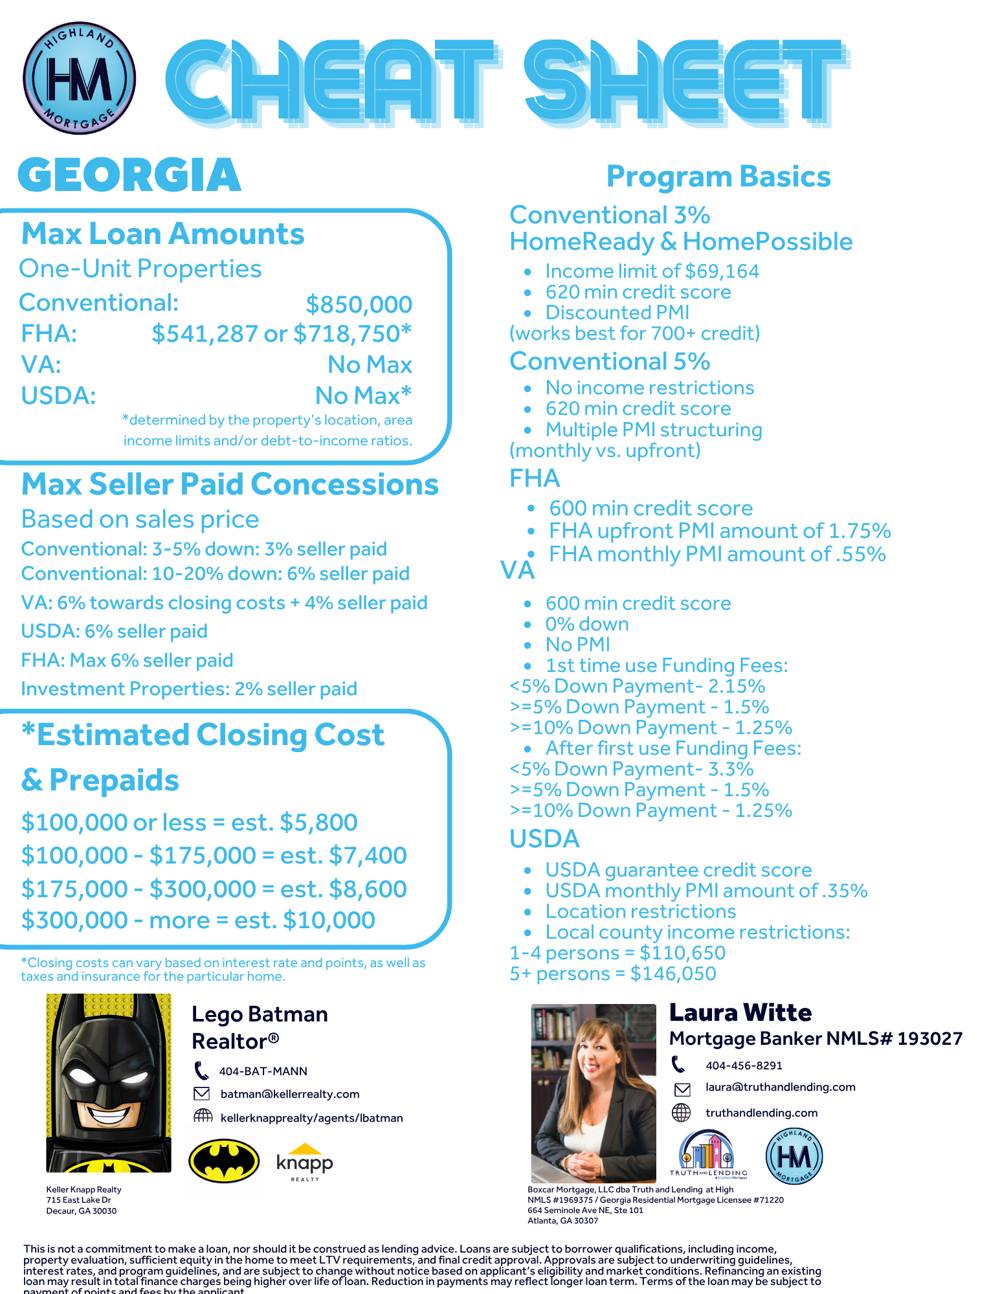
Max seller-paid concessions in Georgia (based on loan type and down payment):
| Loan Type | Max Seller Contribution |
|---|---|
| Conventional, 3–5% down | 3% of sales price |
| Conventional, 10–20% down | 6% of sales price |
| VA | 4% seller paid + 6% toward closing costs |
| USDA | 6% seller paid |
| FHA | Max 6% seller paid |
| Investment Properties | 2% seller paid |
5 Ways to Use a Seller Credit
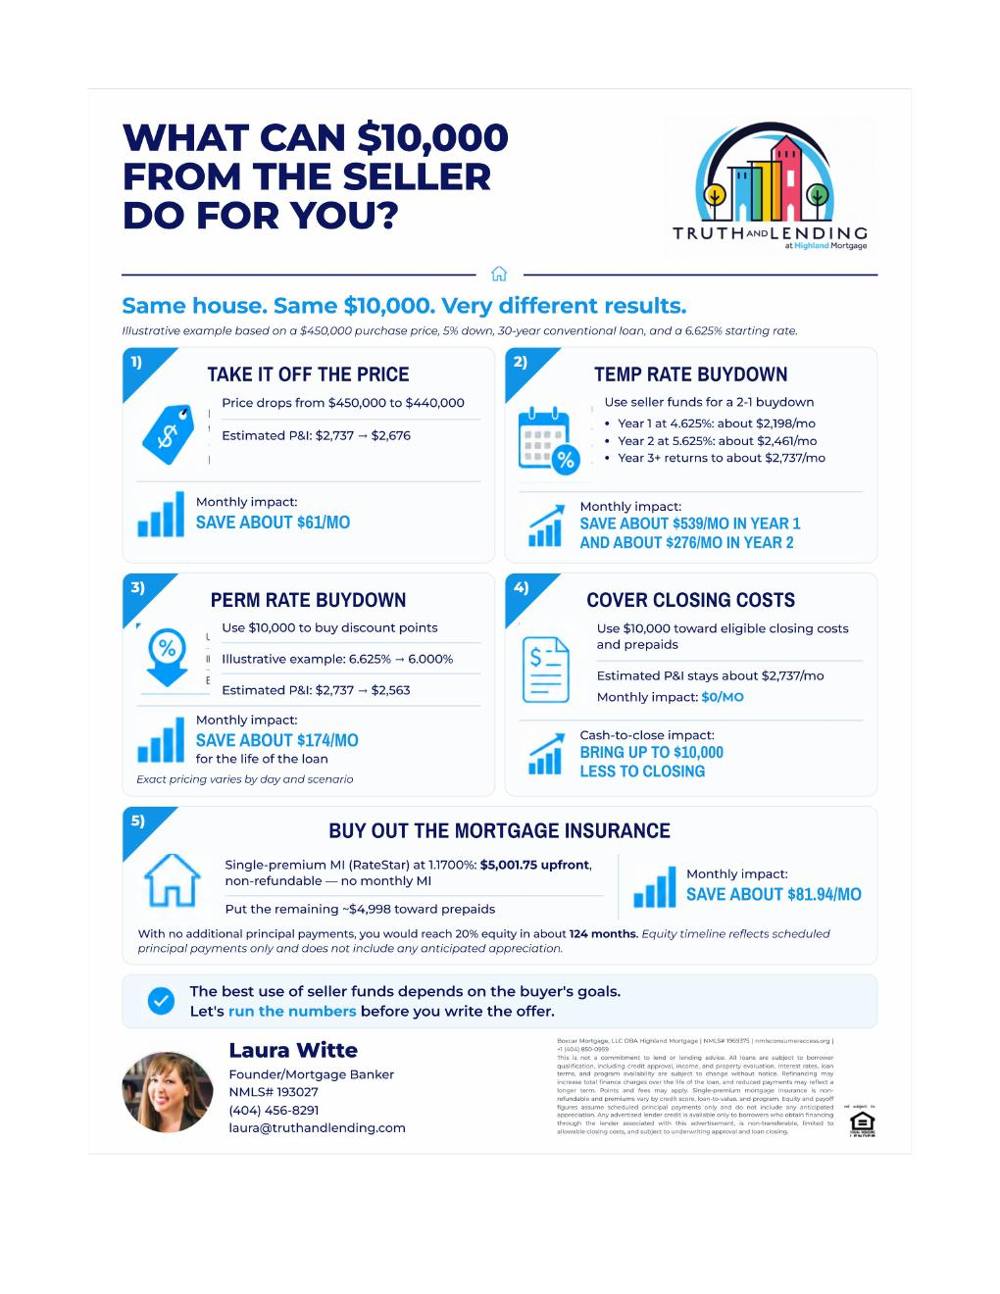
Same house, same $10,000 from the seller — very different results depending on the goal. Tap an option:
Illustrative example: $450,000 purchase price, 5% down, 30-yr conventional, 6.625% starting rate. Exact pricing varies by day and scenario — always run the numbers before writing the offer.
Flyer: What Can $10,000 From the Seller Do For You?
2. Bridge Loan & Zero Payment Reserve
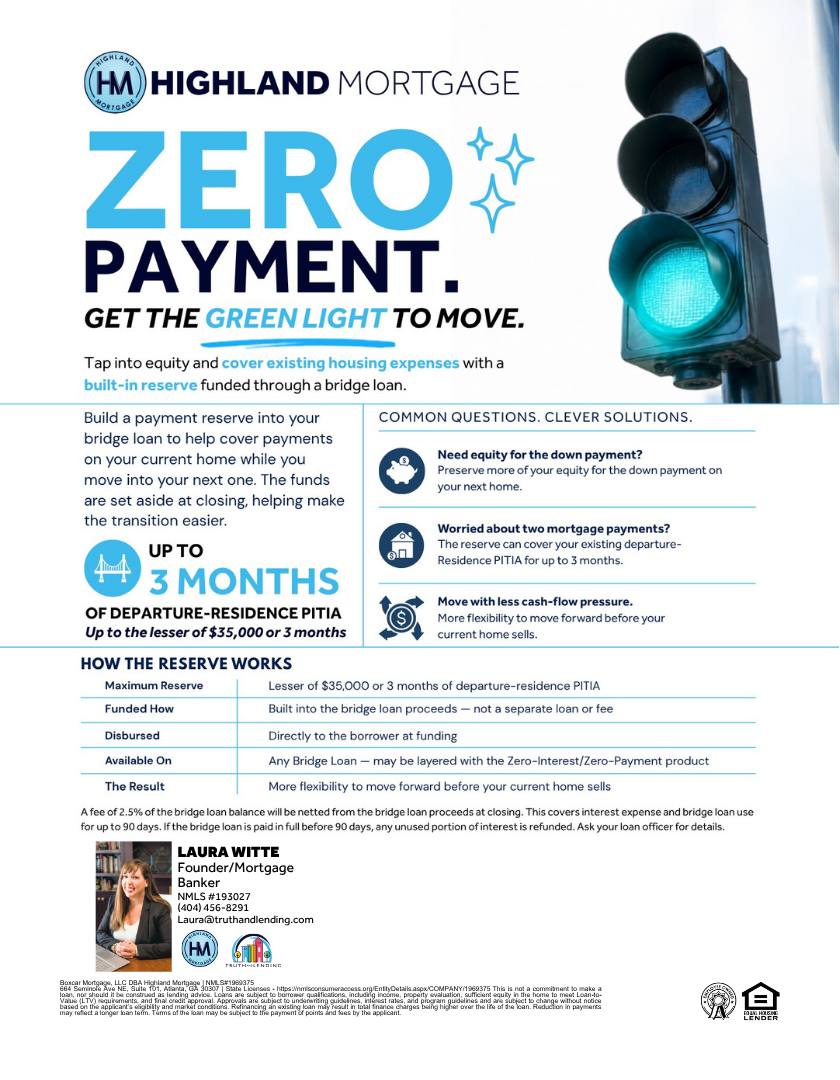
What it solves: Clients often need equity from their current home to buy the next one, but don't want (or can't afford) to carry two payments while they wait to sell. A bridge loan taps into their current home's equity before it sells, and the Zero Payment Reserve builds a cash cushion right into the loan.
- Down payment Preserve more equity for the down payment on the next home instead of draining savings.
- Double payments Reserve covers the departure-residence PITIA for up to 3 months.
- Repairs / changes Use bridge proceeds toward repairs or updates on the new home.
- Debt payoff Free up equity to pay off other debt before or during the move.
- Less pressure More flexibility to move forward before the current home sells.
| Feature | Detail |
|---|---|
| Maximum reserve | Lesser of $35,000 or 3 months of departure-residence PITIA |
| Funded how | Built into the bridge loan proceeds — not a separate loan or fee |
| Disbursed | Directly to the borrower at funding |
| Available on | Any bridge loan — can be layered with the Zero-Interest / Zero-Payment product |
A fee of 2.5% of the bridge loan balance is netted from proceeds at closing, covering interest expense and bridge loan use for up to 90 days. If paid in full before 90 days, any unused portion of interest is refunded.
Quick Reserve Estimator
Flyer: Zero Payment — Get the Green Light to Move
3. Financing the Fixer-Upper
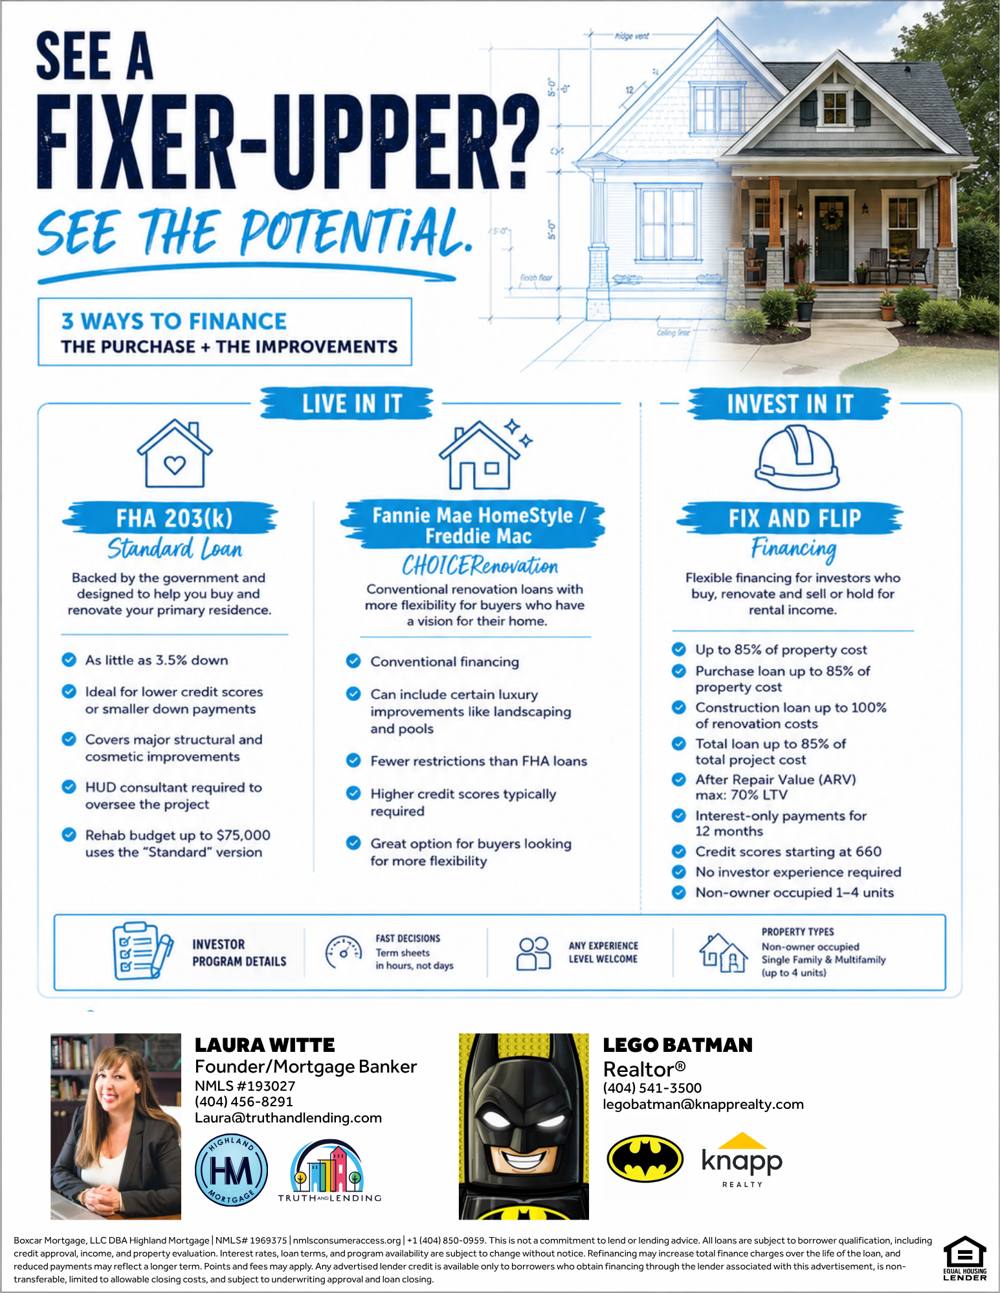
Three ways to finance the purchase and the improvements — whether the client is moving in or investing:
Live In It
FHA 203(k) Standard: as little as 3.5% down, ideal for lower credit or smaller down payments, covers major structural/cosmetic work, requires a HUD consultant, rehab budget up to $75,000 uses the "Standard" version.
Fannie Mae HomeStyle / Freddie Mac CHOICERenovation: conventional financing, can include upgrades like landscaping and pools, fewer restrictions than FHA but typically needs a higher credit score.
Invest In It
Fix and Flip Financing: purchase loan up to 85% of property cost, construction loan up to 100% of renovation costs, ARV max 70% LTV, interest-only for 12 months, credit scores starting at 660, no investor experience required, non-owner occupied 1–4 units.
Flyer: Fixer-Upper Financing
4. Georgia Loan Program Cheat Sheet
Max loan amounts, program basics (Conventional, FHA, VA, USDA), and closing cost estimates for Georgia — all on one reference sheet.
5. Scan to Download All Flyers
Laura Witte
Founder / Mortgage Banker — NMLS# 193027
(404) 456-8291 · laura@truthandlending.com
truthandlending.com


Boxcar Mortgage, LLC DBA Highland Mortgage | NMLS# 1969375 | Laura Witte NMLS# 193027 | 664 Seminole Ave NE, Suite 101, Atlanta, GA 30307
NMLS Consumer Access
This is not a commitment to make a loan, nor should it be construed as lending advice. Loans are subject to borrower qualifications, including income, property evaluation, sufficient home equity to meet Loan-to-Value (LTV) requirements, and final credit approval. Approvals are subject to underwriting guidelines, interest rates, and program guidelines, and are subject to change without notice based on the applicant’s eligibility and market conditions. For licensing info, go to NMLSConsumerAccess.org. Equal Housing Lender.